 Ira Singh
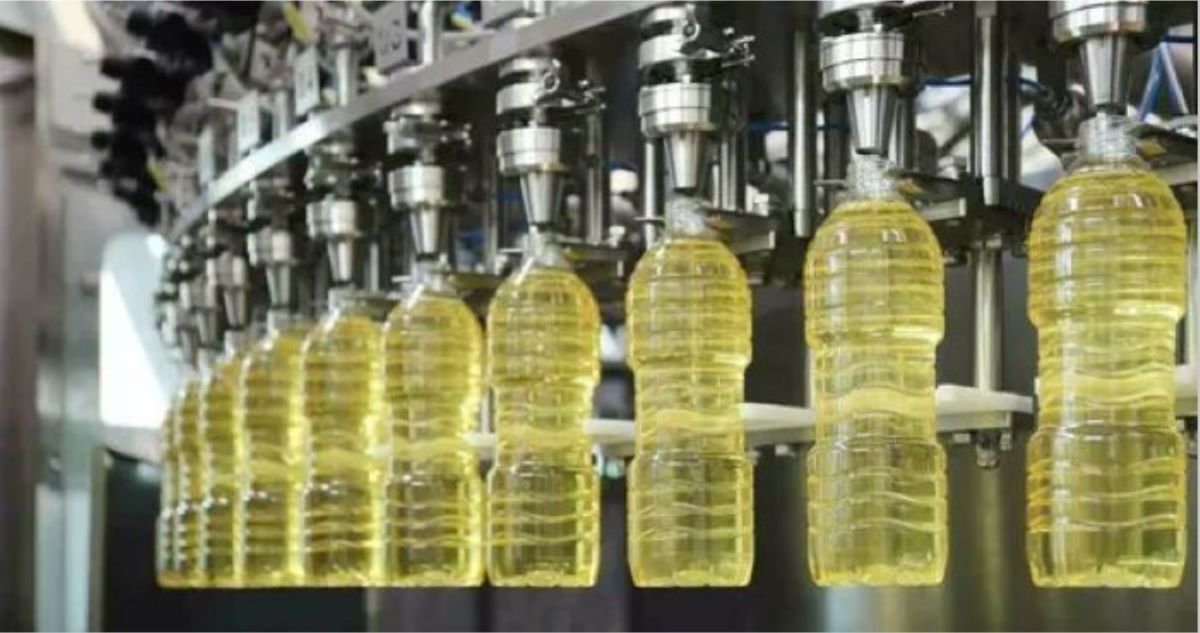
Indonesia’s shift to B50 biodiesel, climate risks and rising crude oil prices are tightening global supplies, exposing India’s heavy dependence on imported cooking oils.Edible oil prices are increasingly being driven by a factor beyond agricultural harvests: fuel policy. As countries divert more vegetable oils towards biodiesel production, the competition between food and fuel is intensifying, pushing prices higher in international markets.
The pressure is evident in the Food and Agriculture Organization’s (FAO) vegetable oil price index, which reached 198.6 points in September, up 18.3% from a year earlier and the highest since June 2022.
For India, the world’s largest edible oil importer, the trend raises concerns about import costs and household food budgets.
Why Are Edible Oil Prices Rising?
Three major forces are converging to tighten global supplies.
•Food versus fuel: Vegetable oils are increasingly being used to produce biodiesel. Around 28% of global palm oil, 25% of soybean oil and 29% of rapeseed oil are diverted towards biodiesel, reducing the supply potentially available for food.
•Indonesia’s B50 mandate: In July 2026, Indonesia raised its mandatory biodiesel blend from B40 to B50, requiring diesel to contain 50% palm oil-based biodiesel. The move is expected to absorb an additional 4.7 million tonnes of palm oil domestically, leaving less available for export.
•Rising crude oil prices: Brent crude trading above $100 a barrel amid the West Asia conflict has strengthened the economic incentive to use vegetable oils for fuel, depending on production costs and government policies.
The shift is not limited to Indonesia. Malaysia began a phased B15 rollout in June 2026, while the United States and the European Union also divert substantial quantities of soybean and rapeseed oil towards biofuels.Even when producing countries maintain substantial output, rising domestic biodiesel demand can reduce export availability and intensify competition among importing nations.
Climate and Shipping Disruptions Add to the Pressure
Energy policies are not the only threat to edible oil supplies. Weather risks and geopolitical disruptions are creating further uncertainty.
•El Niño risk:Dry conditions can damage palm flowering and fruit development, with lower yields potentially emerging eight to 12 months later.
•Black Sea disruption: Restrictions on navigation through the Sea of Azov and suspended Black Sea port operations have complicated sunflower oil shipments from major producing countries, including Russia and Ukraine.
•Substitution effect:When sunflower oil supplies tighten, buyers may turn to palm, soybean or rapeseed oil, spreading price pressure across the wider market.
These factors are making global edible oil supplies more vulnerable to simultaneous shocks in energy, weather and shipping.
Why India Is Particularly Exposed
India imports around 57% of its edible oil requirements, making domestic prices highly sensitive to international market movements.
•Heavy reliance on Southeast Asia:India imported approximately eight million tonnes of palm oil in 2025-26, largely from Indonesia and Malaysia. Any reduction in their export availability can affect India's import costs.
•Record import outlook: India's total edible oil imports could reach 17.2 million tonnes in 2026-27, according to the supplied estimates. Projected imports include 8.2 million tonnes of palm oil, five million tonnes of soybean oil and 3.5 million tonnes of sunflower oil. These figures total 16.7 million tonnes, leaving a discrepancy that needs verification.
•Falling domestic output:Production is projected to decline from 9.7 million tonnes in 2025-26 to 9.2 million tonnes in 2026-27, potentially widening the gap between domestic supply and demand.
Higher international prices can feed into Indian retail prices through landed costs, freight, currency movements, import duties and domestic distribution expenses.
Why India Struggles to Reduce Import Dependence
India's exposure also reflects long-standing weaknesses in domestic oilseed cultivation.
•Monsoon dependence:More than 70% of oilseed cultivation depends on rainfall, leaving production vulnerable to drought and erratic monsoons.
•Limited price assurance:Oilseed farmers lack procurement support on a scale comparable to that available for rice and wheat, potentially discouraging them from expanding cultivation.
•A persistent supply gap:When domestic production falls short, India must buy more from overseas markets, leaving consumers exposed to global price shocks.
What Can India Do?
Reducing edible oil inflation will require a stronger domestic supply base and a more diversified import strategy.
•Expand domestic production:Strengthen the National Mission on Edible Oils, covering oilseeds and oil palm, to advance the 2030-31 self-reliance target.
•Improve farmers' returns:Expand price support and assured procurement where feasible, alongside better seeds, irrigation and farming practices.
•Diversify imports:Broaden sourcing beyond Indonesia and Malaysia wherever commercially viable to reduce dependence on a limited number of suppliers.
The Bigger Picture
Edible oil inflation highlights a growing conflict between food security and energy security. Countries seeking to reduce fossil fuel dependence are increasing demand for vegetable oils, while climate risks and shipping disruptions are limiting the flexibility of global supplies.For India, the challenge is twofold: protect consumers from rising cooking oil prices while making domestic oilseed farming more productive and financially attractive.
Meanwhile, as long as India depends heavily on imported edible oils, decisions on biodiesel blending in Southeast Asia, weather conditions in major producing regions and movements in crude oil prices will continue to influence what Indian households pay for cooking oil, noted experts.
(Business Correspondent)
Related Posts
APEDA flags off FPO-led frozen food export from Haryana to Canada
India cuts edible oil import duty to lower prices ahead of festivals
Peace on border essential for business ties: Modi tells Xi In bilateral