 Newsinc24 Team
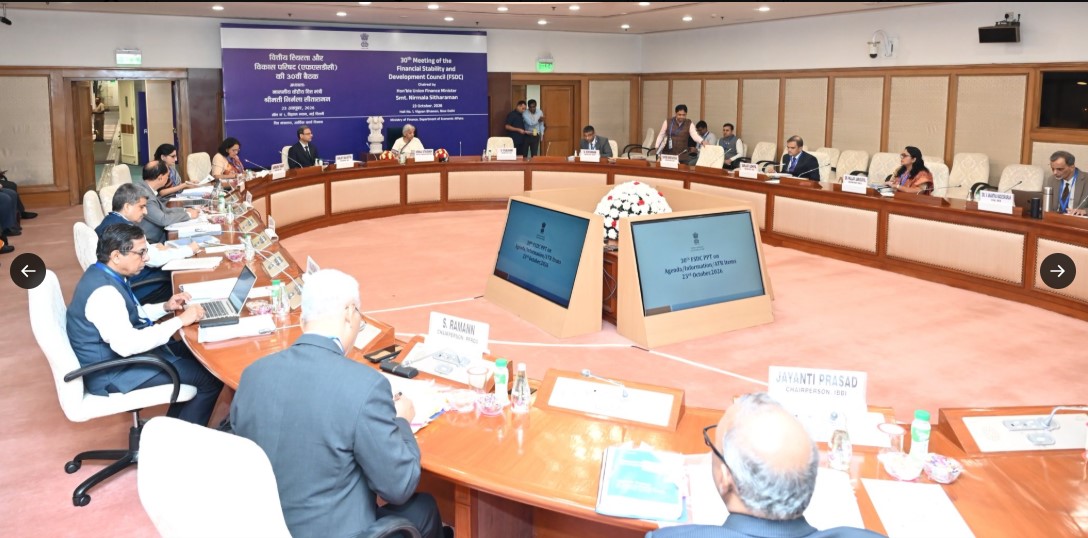
Union Finance Minister Nirmala Sitharaman on Friday chaired the 30th meeting of the Financial Stability and Development Council (FSDC) in New Delhi, reviewing financial stability, cybersecurity preparedness, fintech innovation and emerging risks amid global economic and geopolitical uncertainties.
The Council discussed measures to strengthen India's financial system, promote tokenisation of financial and other real-world assets, improve investment flows and expedite the refund of unclaimed financial assets to their rightful owners, according to a government agency.During the meeting, members reviewed domestic and global macro-financial developments, highlighting the need for vigilance amid geopolitical uncertainties, the artificial intelligence (AI) boom and rising global bond yields. They emphasised proactive measures to mitigate potential risks and maintain the resilience of the financial system.
The Council also discussed regulatory improvements to encourage fintech innovation and strengthen coordination among financial sector regulators. Members explored the potential of tokenisation to facilitate the development of financial markets and other real-world assets.Cybersecurity preparedness was another key focus, with the FSDC taking note of the Financial Sector Cyber Security Strategy formulated by an inter-ministerial group involving financial regulators and cybersecurity agencies. The strategy aims to strengthen the cyber resilience of India's financial sector, including the protection of critical information infrastructure and improved cybersecurity readiness among Regional Rural Banks.
The Council also reviewed measures to strengthen domestic investment and improve resource flows, including through GIFT-IFSC. Discussions covered simplifying and digitising Know Your Customer (KYC) procedures and digital onboarding for Non-Resident Indians and Foreign Portfolio Investors.Members further examined ways to expand Digital Public Infrastructure, including the Account Aggregator framework and Unified Lending Interface, particularly to improve access to credit for micro, small and medium enterprises. Other priorities included reducing financial intermediation costs, improving regulatory responsiveness and rationalising credit guarantee schemes.
Sitharaman urged regulators and other stakeholders to accelerate the refund of unclaimed financial assets, including bank deposits, dividends, shares, post office accounts, insurance proceeds and pension funds. The Council reviewed efforts under the “Your Money, Your Right” campaign and called for intensified action to ensure that such assets reach their rightful owners.In view of growing geopolitical challenges and global uncertainty, the Finance Minister also called for more frequent FSDC meetings according to a predefined schedule. The Council reviewed the activities of its Sub-Committee, chaired by the Reserve Bank of India Governor, and took note of action taken on pending decisions from previous meetings.The meeting was attended by RBI Governor Sanjay Malhotra and senior officials from the Departments of Economic Affairs, Financial Services and Revenue, the Ministry of Electronics and Information Technology, and the Ministry of Corporate Affairs, among others.
Related Posts
India strengthens cultural ties with Sri Lanka through Buddha Relics
India-Poland strategic partnership should translate into JVs: PM Tusk
US National appears before Delhi NIA court in Myanmar arms training case