 Uday Kumar Varma
Part I: How India Learnt to Pay Differently
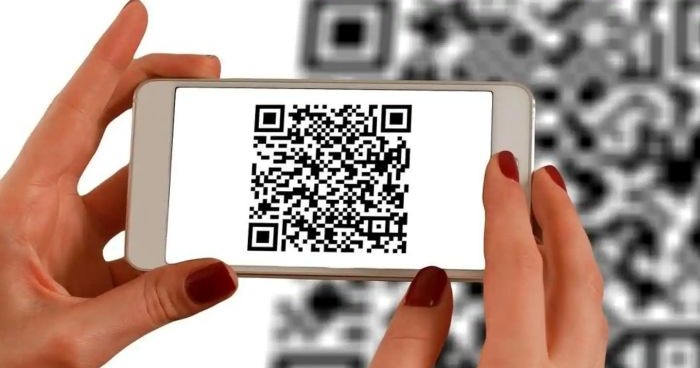
There are technological revolutions that announce themselves with great fanfare, and there are those that quietly become part of everyday life. UPI belongs to the second category. Its most visible symbol is a little black-and-white square that now appears almost everywhere—in the neighbourhood grocery shop, beside a cup of tea, on the dashboard of an autorickshaw and next to the weighing scales of a roadside vegetable vendor.
We scarcely notice it anymore. We simply scan it, enter an amount and move on.
Yet that small QR code conceals one of the more remarkable transformations in India's economic life. The Unified Payments Interface, or UPI, has changed not merely the way Indians pay but, in a larger sense, the way they think about money. Cash has not disappeared, nor is it likely to. But the act of making a payment has become almost invisible.
The idea behind the simplicity
UPI was launched in April 2016 by the National Payments Corporation of India (NPCI), with the Reserve Bank of India as its regulator. The pilot began with a modest group of banks. The underlying idea was deceptively simple: enable a person to transfer money directly from one bank account to another, instantly, through a common interface rather than through the separate systems of individual banks.
The significance of this is easy to underestimate today. Banking systems had traditionally been organised around institutions. If I banked with one institution and you with another, the machinery connecting us was largely invisible and often cumbersome. UPI turned the bank account into the basic unit and the interface into the common language.
That was the breakthrough.
A user did not have to understand how the payment travelled through the banking system. Nor did a small merchant have to invest in expensive card infrastructure. A smartphone and a QR code were enough. The complicated technology remained behind the curtain; the customer saw only simplicity.
Perhaps that was the secret of UPI's extraordinary adoption. India did not ask its citizens to become technologically sophisticated. It made sophisticated technology simple enough for almost anyone to use.
It did not happen in isolation
UPI was also the product of an ecosystem that had been quietly taking shape for several years.
The Jan Dhan Yojana brought millions of people into the formal banking system. Aadhaar provided a widely available digital identity layer. The rapid spread of mobile phones and inexpensive data created the means for people to access digital services. The Reserve Bank itself has described the Jan Dhan-Aadhaar-Mobile combination as an important foundation for India's financial inclusion journey.
UPI connected these pieces.
This is an important part of the Indian story. UPI was not simply a brilliant piece of fintech dropped into an otherwise unchanged economy. It became possible because India had been building the institutional and technological foundations on which it could operate.
Demonetisation in November 2016 provided another powerful, though disruptive, push towards digital payments. For millions of Indians who had rarely used anything other than cash, the circumstances suddenly made digital alternatives relevant. But demonetisation alone cannot explain UPI's subsequent success. What made the change durable was that UPI offered something that cash could not: extraordinary convenience without requiring a new financial relationship.
The QR code did not ask the tea seller to become a banker. It simply gave him another way of accepting payment.
From technology to habit
The real achievement of UPI may therefore be cultural rather than technological.
A payment used to involve a certain amount of ceremony. One counted notes, searched for change, handed over the money and waited for the transaction to be completed. Cards introduced another mechanism, but required a card reader and, usually, a certain degree of infrastructure at the merchant's end.
UPI collapsed much of that process into a few seconds.
The customer could pay ₹10 for tea or ₹1,000 for dinner in almost exactly the same way. A student could send money to a parent. A parent could send money to a child. A shopkeeper could receive payment without worrying about change. A small business could collect money directly into its bank account.
The important point is not merely that the transaction became faster. The friction disappeared.
That matters enormously in a country of India's scale and diversity. Technology succeeds when people stop thinking about the technology itself. We do not admire the telephone every time we make a call. We do not marvel at electricity when we switch on a light. UPI has begun to acquire the same quality of invisibility.
The numbers tell only part of the story
The scale to which this simple idea has grown is extraordinary. NPCI's latest statistics show that in August 2026 UPI processed 24.51 billion transactions, involving nearly ₹29.82 trillion, with 752 banks live on the platform.
Numbers of this magnitude are difficult to visualise. Twenty-four billion transactions in a month means that UPI is no longer merely one payment option among many. It has become a major piece of India's everyday economic infrastructure.
But perhaps the more revealing measure is not the volume of transactions but the range of people making them.
UPI crosses the familiar boundaries of Indian economic life. It is used in air-conditioned stores and in roadside stalls, in large cities and smaller towns, by organised businesses and by people whose businesses may consist of a cart, a counter or a small shop. The same basic system serves all of them.
That universality is what makes the achievement unusual.
The invisible infrastructure
There is, however, a paradox at the heart of this success.
The user sees a QR code and a few seconds of screen activity. Behind it lies a large and sophisticated network—banks, payment applications, servers, telecommunications systems, authentication mechanisms, settlement arrangements and increasingly complex systems for detecting fraud and protecting transactions.
The simplicity experienced by the customer is therefore the result of considerable complexity somewhere else.
This is the point at which the story of UPI becomes larger than the story of a successful payment application. India has created a piece of digital public infrastructure on which millions of commercial and personal transactions now depend.
And infrastructure has a peculiar characteristic: the more successful it becomes, the more invisible it tends to be.
We notice a bridge when it is being built. Once it becomes part of the landscape, we simply drive across it. We notice a payment system when it fails. When it works perfectly, we hardly think about it.
UPI has reached that stage.
A ten-year transformation
Ten years ago, India was still learning to pay without cash. Today, UPI is processing billions of transactions every month and is beginning to attract international attention as an example of how digital payments can be built at population scale.
The journey is not complete. There are questions about cybersecurity, fraud, privacy, financial inclusion and the resilience of a system on which so much everyday commerce now depends. There are also questions about how such an enormous infrastructure should be financed as it grows.
Those questions will become increasingly important precisely because UPI has succeeded so spectacularly.
For the moment, however, it is worth recognising what has already happened. India did not merely digitise an existing payment system. It changed the experience of making a payment.
The little QR code that sits quietly on a tea stall counter is therefore more than a convenient piece of technology. It is the visible end of a much larger Indian experiment in building digital public infrastructure—one that has transformed an everyday economic act into something almost effortless.
The question now is not whether UPI has changed India.
It clearly has.
The more interesting question is how India sustains what it has built—and what it can do with it next.
(Uday Kumar Varma is an IAS officer. Retired as Secretary, Ministry of Information & Broadcasting)


Related Items
Saudi Arabia activates Mecca warning system amid Houthi threat
Agri education system should cater to farmers' needs: Shivraj Singh
Trump praises India's voter ID system in bid to pass SAVE America Act